Understanding Drawdown in Sports Betting: What It Means and Why It Matters
15 Views
08
Oct
2026
Understanding Drawdown in Sports Betting: What It Means and Why It Matters
Sports betting performance is often judged by a simple question:
Did the strategy make a profit?
Profit is important, but it does not tell the complete story.
Two sports betting strategies can produce similar long-term results while experiencing very different levels of risk along the way.
One strategy may grow relatively steadily.
Another may experience large declines, repeated losing periods, and significant pressure on the bankroll before eventually recovering.
This is where drawdown becomes important.
Drawdown is one of the most useful measurements for understanding how much a sports betting strategy can decline during unfavorable periods.
It provides information that profit, win rate, and ROI alone cannot show.
Understanding drawdown can therefore help evaluate risk, bankroll stability, position sizing, and the overall sustainability of a sports betting strategy.
## What Is Drawdown in Sports Betting?
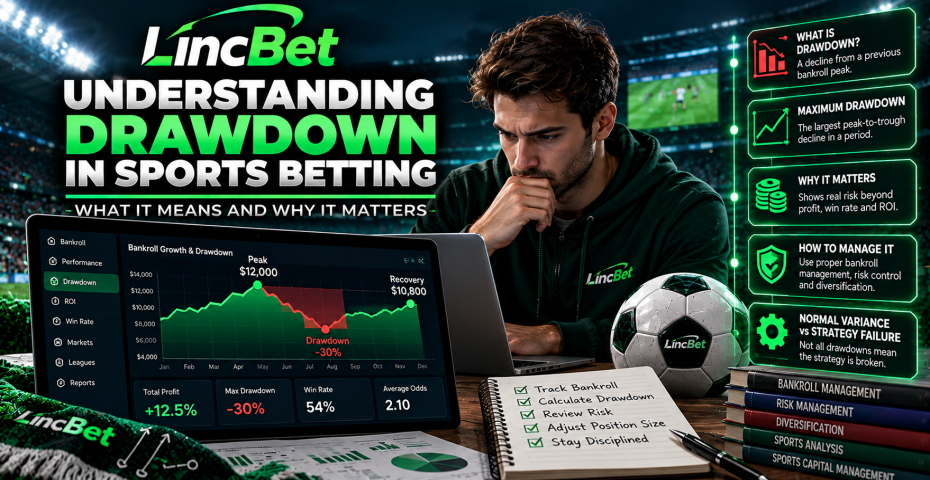
Drawdown measures the decline from a previous bankroll peak to a subsequent lower point.
Suppose a sports betting bankroll begins at $1,000.
Over time, it grows to $1,500.
After a series of unsuccessful results, the bankroll falls to $1,200.
The decline from $1,500 to $1,200 is the drawdown.
In this example:
Peak bankroll = $1,500
Lowest subsequent bankroll = $1,200
Drawdown = $300
Percentage drawdown = 20%
The calculation is:
Drawdown Percentage = (Peak Value - Current or Lowest Value) ÷ Peak Value × 100
Therefore:
($1,500 - $1,200) ÷ $1,500 × 100 = 20%
This tells us that the bankroll declined 20% from its previous peak.
## Drawdown Is Different From a Simple Loss
A loss and a drawdown are related, but they are not the same thing.
A loss refers to the result of an individual position or a group of positions.
Drawdown measures the decline from the highest previous bankroll level.
For example, imagine a bankroll moves like this:
$1,000 → $1,100 → $1,250 → $1,180 → $1,100
The bankroll is still above its original $1,000 starting point.
However, it has declined from its $1,250 peak.
That decline is a drawdown.
The drawdown is:
$1,250 - $1,100 = $150
Or:
12%
This distinction is important because a strategy can remain profitable overall while simultaneously experiencing a significant drawdown.
## What Is Maximum Drawdown?
Maximum drawdown is the largest peak-to-trough decline experienced during a specific period.
Consider this bankroll history:
$1,000
$1,200
$1,500
$1,350
$1,100
$1,300
$1,600
The largest decline occurred when the bankroll fell from $1,500 to $1,100.
That represents:
$400 of drawdown.
Or approximately 26.7%.
Later, the bankroll recovered and reached a new peak of $1,600.
Maximum drawdown records the largest decline experienced before that recovery.
This can be one of the most important measurements when comparing sports betting strategies.
## Why Drawdown Matters
Final profit tells you where the strategy ended.
Drawdown tells you something about the journey required to get there.
Imagine two strategies both finish the year with a 15% increase in bankroll.
Strategy A experienced a maximum drawdown of 8%.
Strategy B experienced a maximum drawdown of 45%.
Their final result may appear similar.
Their risk profiles are not.
Strategy B required the bankroll to survive a much larger decline.
That may indicate more aggressive position sizing, greater concentration, higher variance, weaker diversification, or another form of increased risk.
This is why long-term performance should not be evaluated using return alone.
## Drawdown Reveals Hidden Risk
A strategy can look successful when only its total profit is displayed.
For example:
Starting bankroll: $10,000
Ending bankroll: $12,000
Net growth: 20%
That appears positive.
But suppose the bankroll fell to $5,500 during the period before recovering.
The strategy experienced a very large drawdown.
That information dramatically changes how the performance should be interpreted.
Without drawdown data, much of the strategy's historical risk remains hidden.
## Bankroll Drawdown and Position Size
Position size has a major influence on drawdown.
Larger positions create larger changes in the bankroll when results are unfavorable.
Suppose two strategies make exactly the same selections.
Strategy A risks relatively small portions of its bankroll.
Strategy B uses much larger position sizes.
Even if both strategies have the same win rate, Strategy B may experience much deeper drawdowns.
This demonstrates an important principle:
Selection quality and capital management are separate issues.
A strategy can identify reasonable opportunities but still experience excessive risk because position sizes are too aggressive.
## Drawdown and Bankroll Management
Bankroll management helps determine how much capital can be exposed to individual opportunities.
Drawdown provides feedback about how those rules perform under actual conditions.
If a strategy repeatedly experiences larger drawdowns than expected, several questions should be reviewed.
Are individual positions too large?
Is total exposure too high?
Are too many positions active simultaneously?
Is the strategy concentrated in similar markets?
Are losses becoming correlated?
Has position sizing changed during winning or losing periods?
These questions connect drawdown directly with bankroll management.
## Drawdown and Risk Management
Drawdown is also a key risk-management measurement.
Risk management attempts to control the consequences of uncertainty.
Drawdown shows how those consequences have affected the bankroll historically.
A strategy with repeated deep drawdowns may indicate that existing risk controls are insufficient.
For example, the strategy may need to review:
Maximum exposure.
Position sizing.
Correlation.
Diversification.
Market concentration.
League concentration.
The objective is not necessarily to eliminate drawdown.
That is unrealistic.
The objective is to understand whether the level of drawdown is compatible with the intended strategy.
## Every Strategy Can Experience Drawdown
Drawdown is not automatically evidence of a bad strategy.
Even disciplined strategies can experience losing periods.
Sporting events contain uncertainty.
A strong favorite can lose.
Several well-researched decisions can fail consecutively.
Normal variance can create periods where results move against the strategy.
Therefore, experiencing drawdown does not automatically mean the strategy has stopped working.
The important questions are:
How large is the drawdown?
How long has it lasted?
Is it within the expected range?
Were strategy rules followed?
Has anything fundamental changed?
These questions are more useful than reacting emotionally to the decline itself.
## Drawdown Duration
The size of drawdown is important.
So is its duration.
Drawdown duration measures how long the bankroll remains below a previous peak.
Suppose a bankroll reaches $5,000.
It then declines and takes three months to exceed $5,000 again.
The strategy spent approximately three months in drawdown.
Another strategy may experience the same percentage decline but recover within two weeks.
The financial decline may be similar, but the experience is different.
Long drawdown periods can create psychological pressure and test discipline.
They can also provide useful information about strategy consistency.
## Recovery From Drawdown
An important mathematical reality is that recovering from a percentage loss requires a larger percentage gain.
If a bankroll loses 10%, it does not need exactly 10% growth to recover.
For example:
$1,000 falls 10% to $900.
To return from $900 to $1,000 requires approximately 11.1% growth.
The effect becomes more significant as drawdown increases.
A 20% drawdown requires 25% growth to recover.
A 30% drawdown requires approximately 42.9%.
A 50% drawdown requires 100% growth.
This is one reason why controlling severe drawdowns can be important.
The deeper the decline becomes, the more difficult the recovery mathematically becomes.
## Drawdown Recovery Examples
Consider a bankroll starting at $10,000.
After a 10% drawdown:
Bankroll = $9,000
Required recovery = approximately 11.1%
After a 20% drawdown:
Bankroll = $8,000
Required recovery = 25%
After a 30% drawdown:
Bankroll = $7,000
Required recovery = approximately 42.9%
After a 40% drawdown:
Bankroll = $6,000
Required recovery = approximately 66.7%
After a 50% drawdown:
Bankroll = $5,000
Required recovery = 100%
This demonstrates why drawdown management deserves attention even when the long-term strategy is expected to experience normal fluctuations.
## What Causes Drawdown?
Drawdown can result from many factors.
Some are normal.
Others may indicate weaknesses in the strategy.
Common causes can include:
Normal statistical variance.
A sequence of unfavorable sporting outcomes.
Position sizes that are too large.
Excessive total exposure.
Poor diversification.
Correlated positions.
Changes in market conditions.
Weak sports analysis.
Outdated information.
Emotional betting decisions.
Chasing losses.
Strategy drift.
A strong performance review should try to determine which factors are contributing to the decline.
## Normal Variance vs Strategy Failure
One of the most difficult questions is determining whether drawdown represents normal variance or a deeper problem.
There is no simple rule that works for every strategy.
However, several indicators can help.
If the strategy continues to follow its established rules, position sizing remains controlled, the analytical process has not changed, and the drawdown remains within historically expected levels, normal variance may be a reasonable explanation.
If the strategy begins violating its own rules, taking larger risks, entering unfamiliar markets, or producing losses far beyond previous historical ranges, further investigation may be necessary.
This is why records and historical performance data are so valuable.
Without them, it is difficult to know what "normal" looks like.
## Maximum Drawdown as a Strategy Comparison Tool
Suppose two strategies produce the following historical results.
Strategy A:
ROI: 12%
Maximum Drawdown: 7%
Strategy B:
ROI: 15%
Maximum Drawdown: 32%
Looking only at ROI, Strategy B appears stronger.
But when drawdown is included, the comparison becomes more complex.
Strategy B generated slightly higher returns while experiencing significantly larger declines.
Whether that risk is acceptable depends on the objectives and structure of the strategy.
The example demonstrates why return should be considered alongside risk.
## Drawdown and Diversification
Diversification can influence drawdown by reducing excessive dependence on a single event or scenario.
Consider a strategy that places most of its capital on one league, one team, or one type of market.
If conditions affecting that category become unfavorable, many positions may perform poorly at the same time.
A more diversified approach can distribute exposure across different opportunities.
However, diversification does not guarantee smaller drawdowns.
Poorly selected positions can still lose together.
The objective is to reduce unnecessary concentration, not to eliminate uncertainty.
## Correlation Can Increase Drawdown
Correlation is especially important.
Several positions may appear different but depend on the same underlying assumption.
Imagine positions involving:
A team to win.
The same team to score multiple goals.
One of its forwards to score.
An over-goals market in the same match.
If the team performs poorly, several positions may lose simultaneously.
This can create a larger drawdown than expected.
Monitoring correlated exposure can therefore be an important part of drawdown control.
## Drawdown and Odds
Odds can also influence the pattern of drawdown.
Strategies operating at higher odds may experience lower win rates and longer losing sequences even if they remain viable over time.
Strategies operating at lower odds may produce more frequent wins but can still suffer significant declines when position sizes are too aggressive or losses cluster together.
This is why drawdown should always be interpreted within the context of the strategy.
There is no universal drawdown level that is automatically good or bad for every betting approach.
## Losing Streaks and Drawdown
Losing streaks are one of the most visible causes of drawdown.
However, the probability of losing streaks is often underestimated.
Even a strategy with a historically positive win rate can experience several consecutive losses.
This is especially important when position sizes are large.
A streak of five losses with small exposure may be manageable.
The same streak with aggressive exposure can produce severe bankroll damage.
Position sizing should therefore consider not only individual event risk but also the possibility of multiple unfavorable outcomes occurring consecutively.
## Do Not Chase Drawdown
One of the worst responses to drawdown is automatically increasing exposure in an attempt to recover faster.
Suppose the bankroll declines by 15%.
A bettor may feel pressure to return to the previous peak quickly.
Position sizes increase.
Risk limits are ignored.
The strategy becomes more aggressive.
If unfavorable results continue, the drawdown can accelerate.
This behavior transforms a normal decline into a potentially much larger problem.
Recovery should come from the strategy operating according to its rules, not from emotional attempts to force the bankroll back to its previous peak.
## Winning Streaks Can Create Future Drawdown
Drawdown management begins before losses appear.
During winning periods, confidence may increase.
A strategy that originally used disciplined position sizes may gradually become more aggressive.
Larger amounts are exposed because recent results create the impression that the method is unusually reliable.
When normal variance eventually returns, the increased exposure can produce deeper drawdowns.
This is another reason why capital-management rules should remain consistent during both winning and losing periods.
## Monitor Drawdown in Percentage Terms
Absolute monetary drawdown is useful, but percentage drawdown often provides better context.
A $500 decline means something very different for a $2,000 bankroll than for a $50,000 bankroll.
Percentage measurement allows comparisons across different bankroll sizes and periods.
It can also help evaluate whether risk has changed as capital grows or declines.
## Track Drawdown Over Time
A drawdown chart can be useful when evaluating strategy performance.
Instead of only recording profit and loss, track the distance between the current bankroll and its previous highest value.
This can reveal patterns.
Are drawdowns becoming deeper?
Are recovery periods becoming longer?
Does one particular market create most of the decline?
Does one league repeatedly contribute to drawdown?
Do large declines occur after position sizes increase?
Historical patterns can help identify areas that deserve review.
## Segment Drawdown by Strategy Component
Overall drawdown provides a useful summary.
More detailed analysis can identify where the decline comes from.
Drawdown can be reviewed by:
Sport.
League.
Market.
Odds range.
Position size.
Day or period.
Pre-match vs live activity.
This segmentation may reveal that most of the overall drawdown comes from a relatively small part of the strategy.
That information can support more targeted improvements.
## Drawdown and Sample Size
Drawdown conclusions should consider sample size.
A very short performance history may not reveal the full risk of a strategy.
For example, a strategy that has only experienced 20 positions may show a maximum drawdown of 5%.
That does not guarantee that 5% represents its true long-term maximum risk.
As the number of observations grows, the strategy may encounter more difficult sequences.
Historical maximum drawdown should therefore be treated as evidence of what has occurred, not a guarantee of the largest possible future decline.
## Drawdown and Strategy Evaluation
Drawdown should be considered alongside several other performance measurements.
These may include:
ROI.
Win rate.
Average odds.
Total profit or loss.
Sample size.
Bankroll growth.
Position consistency.
Exposure.
Diversification.
No single statistic can provide a complete evaluation.
Together, these measurements create a more balanced picture.
## Should a Strategy Stop at a Certain Drawdown?
Some strategies define predefined drawdown thresholds.
For example, reaching a particular decline may trigger a review, reduced exposure, or temporary suspension.
The appropriate rule depends on the strategy.
The important principle is that the response should ideally be defined before emotional pressure appears.
A predefined rule creates consistency.
Waiting until the bankroll is already under significant pressure can lead to emotional decisions.
## A Drawdown Review Process
When drawdown reaches an unusual level, the strategy can be reviewed systematically.
Ask:
Were all positions consistent with the strategy?
Were stake sizes within established limits?
Did total exposure become excessive?
Were positions correlated?
Did the quality of analysis decline?
Did market conditions change?
Were emotional decisions introduced?
Is the drawdown significantly larger than historical experience?
Is the sample large enough to support conclusions?
These questions help separate normal variance from structural problems.
## Drawdown Is Not a Reason to Rewrite Everything
Another common mistake is making major strategy changes during every losing period.
If the system changes constantly, it becomes impossible to evaluate consistently.
Short-term drawdowns can occur even within disciplined strategies.
Adjustments should generally be based on meaningful evidence rather than the discomfort of a temporary decline.
This does not mean ignoring problems.
It means distinguishing between evidence-based improvement and emotional reaction.
## Drawdown and Sports Analysis
Poor analytical decisions can contribute to drawdown.
If inaccurate data, weak assumptions, or outdated team information repeatedly influence selections, performance may deteriorate.
Reviewing the analytical process can therefore form part of drawdown analysis.
However, a losing result does not automatically mean the analysis was poor.
The process should be evaluated separately from individual outcomes.
Good sports analysis reduces uninformed decisions.
It does not eliminate uncertainty.
## Drawdown Within Sports Capital Management
Drawdown is especially relevant within the broader concept of sports capital management.
Sports capital management considers not only which opportunities are selected but also how available capital is allocated and protected.
Within this framework, drawdown provides information about how the entire strategy behaves during unfavorable periods.
It connects several important concepts:
Bankroll management.
Risk management.
Capital allocation.
Diversification.
Position sizing.
Performance evaluation.
This makes drawdown more than just another statistic.
It becomes a practical measure of how the capital-management framework responds to uncertainty.
## LincBet and Structured Risk Evaluation
LincBet approaches sports-related activity through a structured sports capital management model.
Within a structured framework, performance should not be evaluated only by successful events or headline returns.
Risk exposure, bankroll behavior, diversification, and periods of decline also matter.
Drawdown can help provide this broader perspective.
It shows how strategy performance behaves when results move away from previous peaks.
This information can contribute to a more complete understanding of both performance and risk.
## Can Drawdown Be Eliminated?
No.
Any sports betting strategy that experiences both wins and losses can experience drawdown.
Trying to eliminate all drawdown would generally require eliminating meaningful exposure altogether.
The realistic objective is not zero drawdown.
It is controlled drawdown consistent with the strategy's intended risk level.
A strategy should be prepared for unfavorable periods before they occur.
## Responsible Drawdown Management
Drawdown should never become a reason to expose essential personal funds in an attempt to recover.
The bankroll should remain separate from money required for living expenses and financial obligations.
If losses create pressure to increase position sizes, borrow money, or abandon predefined limits, the appropriate response is not greater exposure.
Reducing or stopping activity may be necessary.
Risk management includes protecting financial boundaries as well as measuring strategy performance.
## Final Thoughts
Drawdown is one of the most important measurements for understanding sports betting risk.
Profit tells you how much a strategy gained or lost overall.
Drawdown shows how far the bankroll declined from a previous peak during the journey.
Maximum drawdown reveals the largest historical decline.
Drawdown duration shows how long the strategy remained below its previous high.
Recovery percentages demonstrate why deeper declines become increasingly difficult to overcome.
Together, these measurements help provide a more complete picture of strategy performance.
A strong evaluation should therefore consider not only:
How much did the strategy make?
But also:
How much risk did the strategy experience to achieve that result?
Understanding this relationship between performance and risk is a central part of structured bankroll management, risk control, and sports capital management.
LincBet